Skip to free estimate

Independent diminished value appraisals

Your car was repaired.
Its value wasn’t.

An accident stays on your car’s history. We document the value it lost and prepare the appraisal and demand letter for your insurance claim.

Check my claim for free

Takes about 2 minutes. Email required for your estimate and follow-ups. Unsubscribe anytime. Paid appraisals start at $199.

Before the accident

$30,000

Market value with a clean history

After repairs

$26,500

Market value with accident history

Diminished value$3,500
Illustrative example. Actual diminished value varies by vehicle and accident.

How it works.

Check your eligibility.

Answer a few questions about your accident and vehicle. Enter your name and email and your estimate appears right away, with a copy sent to your inbox. Paid appraisals start at $199.

Get your appraisal.

Choose your report and upload your repair documents. We prepare and personally review your appraisal.

Submit your claim.

Send your appraisal and demand letter to the insurer. When they answer, forward it to me and I’ll write your reply.

*Report delivery within 2 business days of receiving your completed intake and all required documentation.

★★★★★Client reviews
“They really did do what they represented they could and would! … THEY followed up with me before I needed to reach out … There was no over-promising either! I cannot recommend this particular service enough.”

Suzanne F. · Our first clientRead the full review on Google →

“DEFINITELY worth the price, Bryan is very knowledgeable about this, you can’t go wrong here”

Doug T. · Google review, October 2026

Already got an offer from the insurer?

Before you accept it, let me look at it. Free.

Forward me the insurer’s offer, or just tell me what they said, and I’ll tell you within one business day whether it’s fair or worth fighting. No payment, no obligation. And if it’s a fair offer, I’ll tell you to take it.

Email me the offer →
Free Estimate

Is a diminished value report worth it for your car?

Answer a few questions, then enter your name and email to receive your estimate by email. We’ll also follow up about ordering; unsubscribe anytime. No payment required. Paid appraisals: $199 standard or $249 structural.

Free, about 1 minute, no credit card. Enter your email at the end to see your estimate.

Step 1 of 8
Example estimates from this tool
2021 Explorer · frame repair$2,300 – $4,700
2022 RAV4 · body and paint$500 – $1,300
Did another driver cause this accident?
DV claims are filed against the at-fault driver's insurance — not your own.
Yes — the other driver was at fault
Most common scenario — you very likely qualify
Not sure yet — fault is still being determined
No problem — we can still estimate your potential recovery
Partially — we both share some fault
You may still qualify if the other driver shares any responsibility
Other driver was at fault but had no insurance
Without a third-party insurer there's no DV claim to pursue
No — I caused the accident
DV claims require an at-fault third party — you likely won't qualify

“They really did do what they represented they could and would!” Our first client’s Google review

Step 2 of 8
When did the accident happen?
DV claims have a filing deadline that varies by state — often two to three years.
Within the last 12 months
1 – 2 years ago
2 – 3 years ago
More than 3 years ago
Step 3 of 8
Have you already settled or signed a release for this claim?
Signing a full release for the damage claim usually waives the diminished value too.
No — my claim is still open
I only settled the repair cost — no full release
Yes — I signed a full release / final settlement
Step 4 of 8
What state did the accident happen in?
We serve 48 states. We do not serve Nebraska or Oregon.
Step 5 of 8
How much were the repairs?
Use the repair estimate or the final bill. Not sure yet? Choose that and we’ll estimate from the rest.
Under $1,500
$1,500 – $3,500
$3,500 – $7,000
Over $7,000
Not sure yet: still waiting on the estimate or bill
My car was declared a total loss
Step 6 of 8
Tell us about your vehicle.
Newer, lower-mileage vehicles have higher DV recovery potential.
What year is your vehicle?
Make
Model
Trim level (optional)
Approximate mileage? (optional)
Title status before the accident?
Step 7 of 8
What did the repairs involve?
Check your repair invoice if you have it. This decides which report you need.
Frame or structural repair: frame straightening, rails, pillars or unibody sections, or airbags deployed
Mechanical parts replaced: steering, suspension, axle or wheels (along with body work)
Body and paint only: panels, bumpers, paint, glass
Not sure: I'd need to check the repair invoice
Step 8 of 8
Did your vehicle have any prior accident history before this claim?
Previous accidents reduce a vehicle's pre-loss value and can lower your DV recovery.
No — clean history before this accident
Yes — minor prior damage (no structural)
Yes — significant prior damage
Email required for your estimate · No payment required

A claim backed
by evidence.

You receive a personally reviewed appraisal, a letter to send to the insurer, and guidance for following up.

Independent diminished value appraisal

A documented assessment of your vehicle’s lost market value, using its condition, repair history, and market comparisons.

A demand letter for your insurer

Your claim laid out in writing, ready for you to review and send with the appraisal.

Someone in your corner until it settles

When the insurer answers, I write your reply. You also get insurer strategy notes and a Department of Insurance complaint letter if they stall.

Your claim, handled. One flat fee.

Not sure it's worth it yet? Email your repair invoice to [email protected] and I'll tell you within one business day, free, whether your claim is worth going after.

Standard

For cosmetic repairs: panels, paint, dents, or glass, with no structural damage.

$199$399
  • A signed appraisal of what your car lost, with every comparable vehicle disclosed
  • A demand letter ready to send, built on real market data instead of a formula
  • I write your reply to every insurer response until your claim settles

Structural

For frame or unibody damage, structural repairs, or airbag deployment.

$249$499
  • Everything in Standard
  • A Structural Impact Statement and frame-damage history analysis
  • Stronger demand language for structural claims

A clear guarantee

If the diminished value we document is less than your report fee, we refund the fee in full. The only time you pay is when we found you more lost value than you paid us. Worst case, you’re out nothing. See our terms.

Ready in 2 business days, then I stay with you

Your report arrives within 2 business days of a complete file. When the insurer answers, forward it to me and I'll write your reply, usually within one business day. No percentage of your settlement, ever.

★★★★★Client reviews
“There was no over-promising either!”
“DEFINITELY worth the price, Bryan is very knowledgeable about this, you can’t go wrong here”

Both of my settled clients finished well above the insurer's first offer: one by more than a third, one by more than half.

Before you accept an offer or sign anything from the insurer, check with me. Once you sign a release, the claim is usually closed for good.
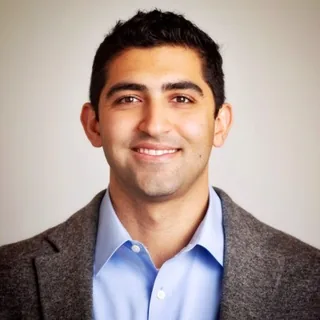
Bryan Dastmalchi, founder of Value Reclaimed

Personally reviewed.
Personally accountable.

I’m Bryan Dastmalchi, founder of Value Reclaimed. I spent fourteen years in finance assessing value and defending the numbers. I personally review and sign every report we deliver.

If you have a question before ordering, email me directly at [email protected].

Still have questions?

What if my claim was already settled?
+
It depends on what you signed. If you signed a full release that specifically included diminished value, you may have waived your right. If the settlement only covered repairs and medical bills, your DV claim may still be open. When in doubt, get the free estimate — it costs nothing to find out.
What states do you serve?
+
We serve clients in 48 states. We do not serve Nebraska (no established legal basis for third-party DV claims) or Oregon (Oregon law requires DV reports to be signed by a state-licensed appraiser, a credential we do not hold).
What's your refund policy?
+
Simple: if the diminished value we document is less than the cost of the report, you get a full refund. If we can't find you more than you paid us, you don't pay. The free estimate screens your claim before you pay, and if your documents show it doesn't qualify after you've ordered, you get your money back.
How do I know Value Reclaimed is legitimate?
+
Payment runs through Stripe, so we never see your card details. You can view a full sample report before paying, so you know exactly what you're buying. Every report is prepared and signed by a named appraiser — Bryan Dastmalchi, founder — not an anonymous company. And the guarantee is simple: if the diminished value we document is less than the cost of your report, you don't pay. We also decline cases that don't qualify, free, at the estimate stage.
How long does it take to get my report?
+
Standard turnaround is 2 business days from the time you submit your completed intake form with all required documentation. In most cases it's faster. Your full appraisal, demand letter, DOI complaint letter, and insurer strategy notes are delivered by email — all human-reviewed before they leave our desk.
What do I need to upload?
+
The main thing you need is your repair invoice — the itemized estimate or final bill from the body shop showing the total repair cost. If you have the other driver's insurance claim number, that's helpful but not required. We'll guide you through everything on the intake form after payment. Most people complete it in under 10 minutes.
What if the insurer ignores my demand letter or lowballs me?
+
Forward me whatever they send. I write your reply to every insurer response until your claim settles, citing the evidence in your report, and you send it. If they stall, your report includes a Department of Insurance complaint letter ready to file. A regulatory complaint creates a paper trail insurers would rather avoid.
Do I need a lawyer?
+
No. The demand letter, DOI complaint, and the replies I write for you are designed to be sent directly by you, without any legal representation. Most DV claims settle through the insurer's claims process without ever involving an attorney or court. If your claim is unusually large or the insurer is actively hostile, an attorney may be worth consulting — but the vast majority of clients handle this entirely on their own.
Who generates my report?
+
Every report is built on a USPAP-informed methodology, drafted with software assistance, then checked line by line, approved and signed by Bryan Dastmalchi before it leaves the desk. Nothing is outsourced, and if it wouldn't pass a professional valuation review, it doesn't ship.

Find out if your car has a claim.

Check your eligibility before paying for an appraisal.

Check my claim for free
Get Free Estimate — No Credit Card →
Sample Report
What's included — Standard Report
★★★★★“They really did do what they represented they could and would!” — our first client’s Google review
Personally reviewed & signed by Bryan Dastmalchi, founder

By clicking you agree to our Terms of Service. Secure checkout via Stripe — we never see your card details.

What Is Diminished Value?
01
The accident creates a permanent record
The repair gets paid and the car looks fine — but the accident is now permanently on your Carfax. Every future buyer and dealer will see it. That record doesn't disappear after repairs.
02
Your car is worth thousands less — permanently
Buyers discount accident-history vehicles significantly. The same car with a clean Carfax sells for measurably more. That gap between what your car would have been worth vs. what it's worth now is your diminished value.
03
In 48 states, the at-fault insurer owes you that loss
The law in most states requires the at-fault driver's insurer to compensate you for diminished value — not just repair costs. Insurers won't volunteer this. Most people never know to ask.
04
But you need documented proof to collect
A verbal claim won't hold. You need a USPAP-informed appraisal backed by real market comp data, a demand letter written for your specific insurer, and a strategy for when they push back. That's what we build.